Proven Performance
From Liability to Asset

LDP Group provides a seamless, end-to-end real estate service designed for expats in Germany. From identifying high-potential properties to securing optimal financing, we manage every step, including tenant placement, rental management, and coordination with trusted tax specialists. Beyond the first purchase, we work with you on a tailored long-term portfolio strategy, ensuring your investments grow in value, generate steady income, and maximize the unique tax advantages of the German real estate market.

location mark Appenzeller Str, Munich
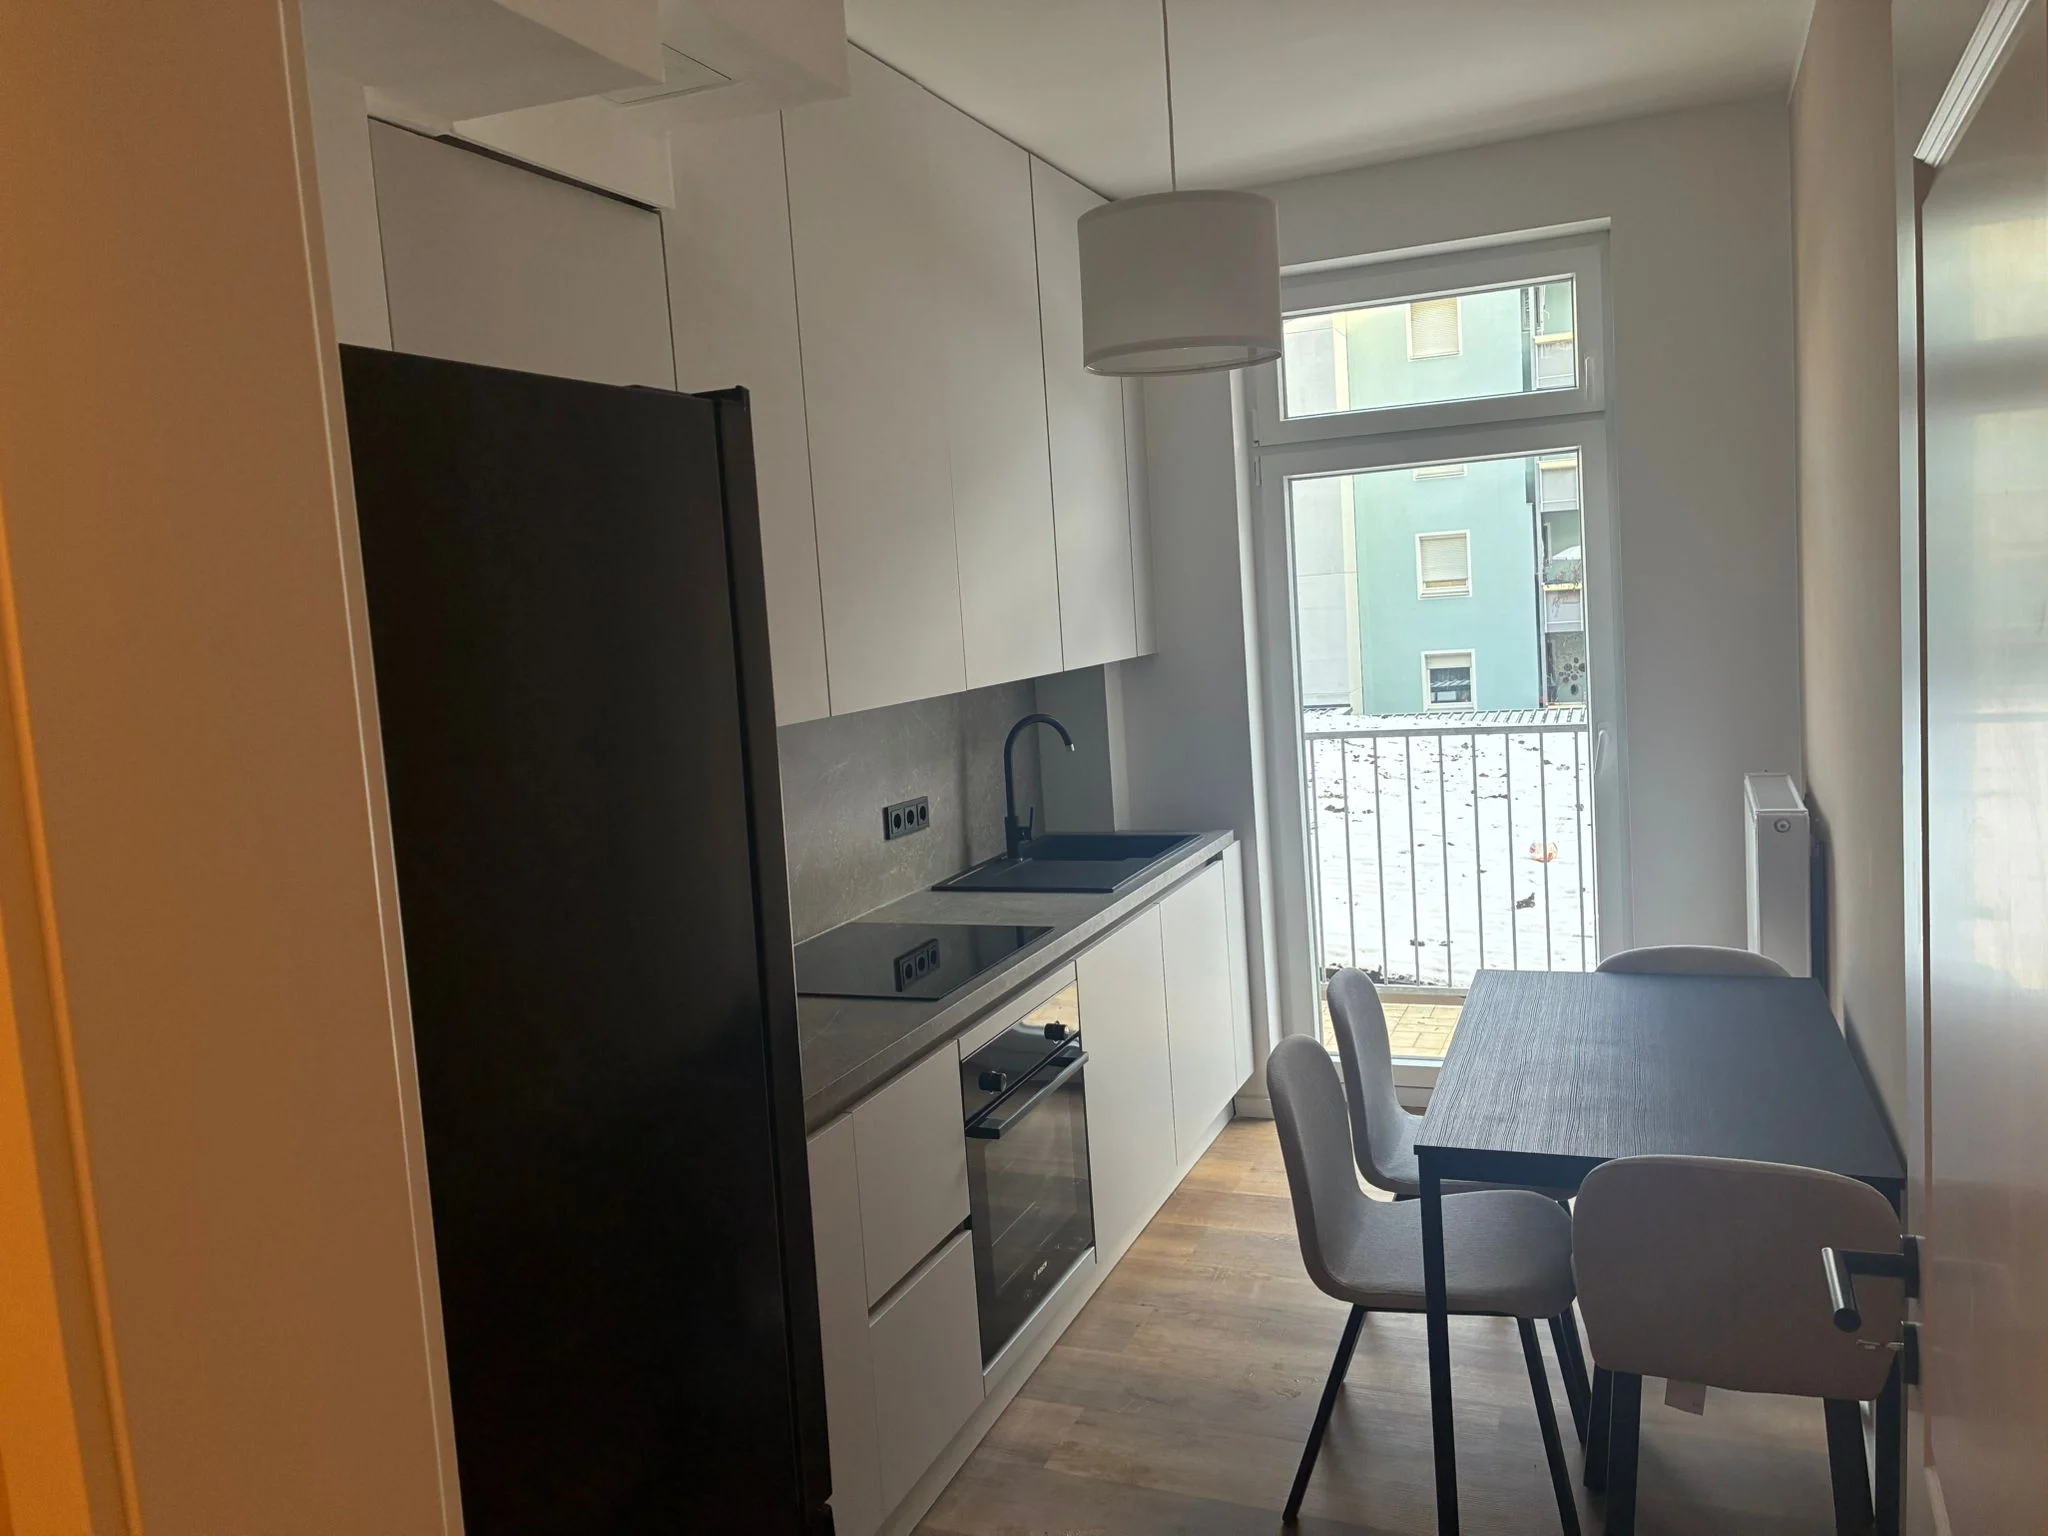
watermark
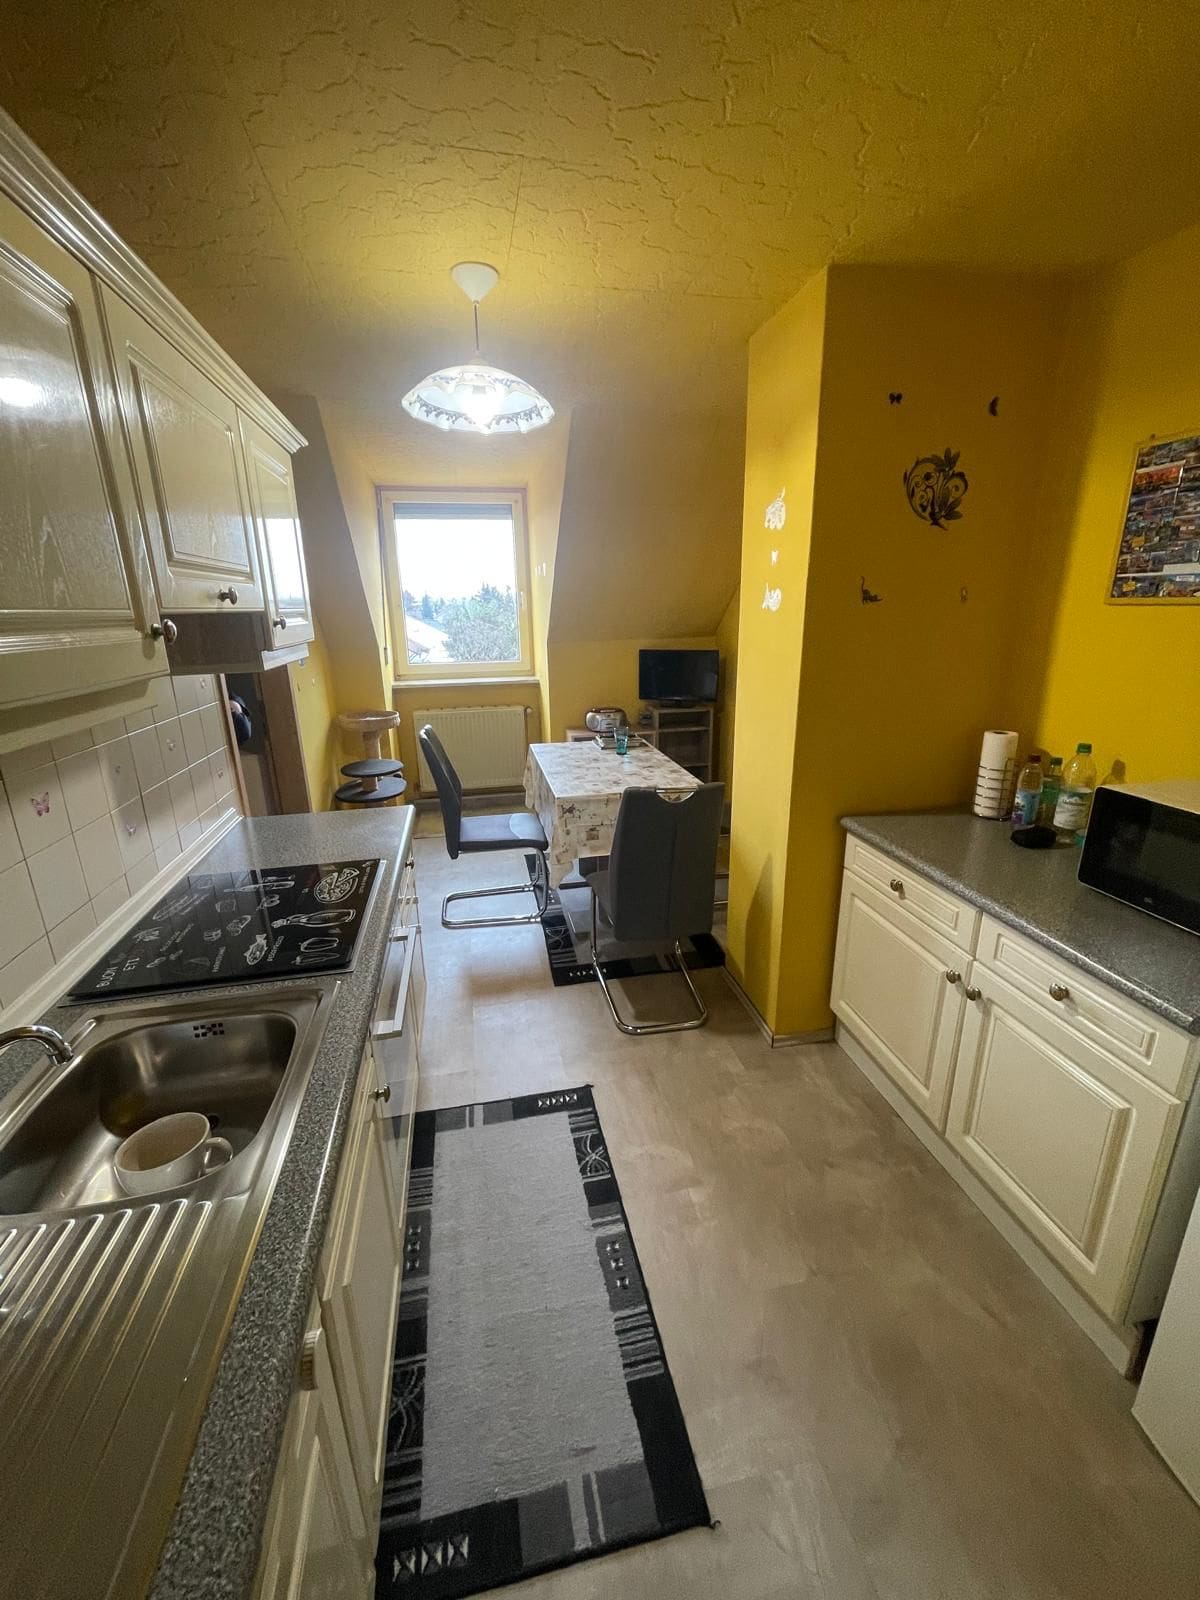
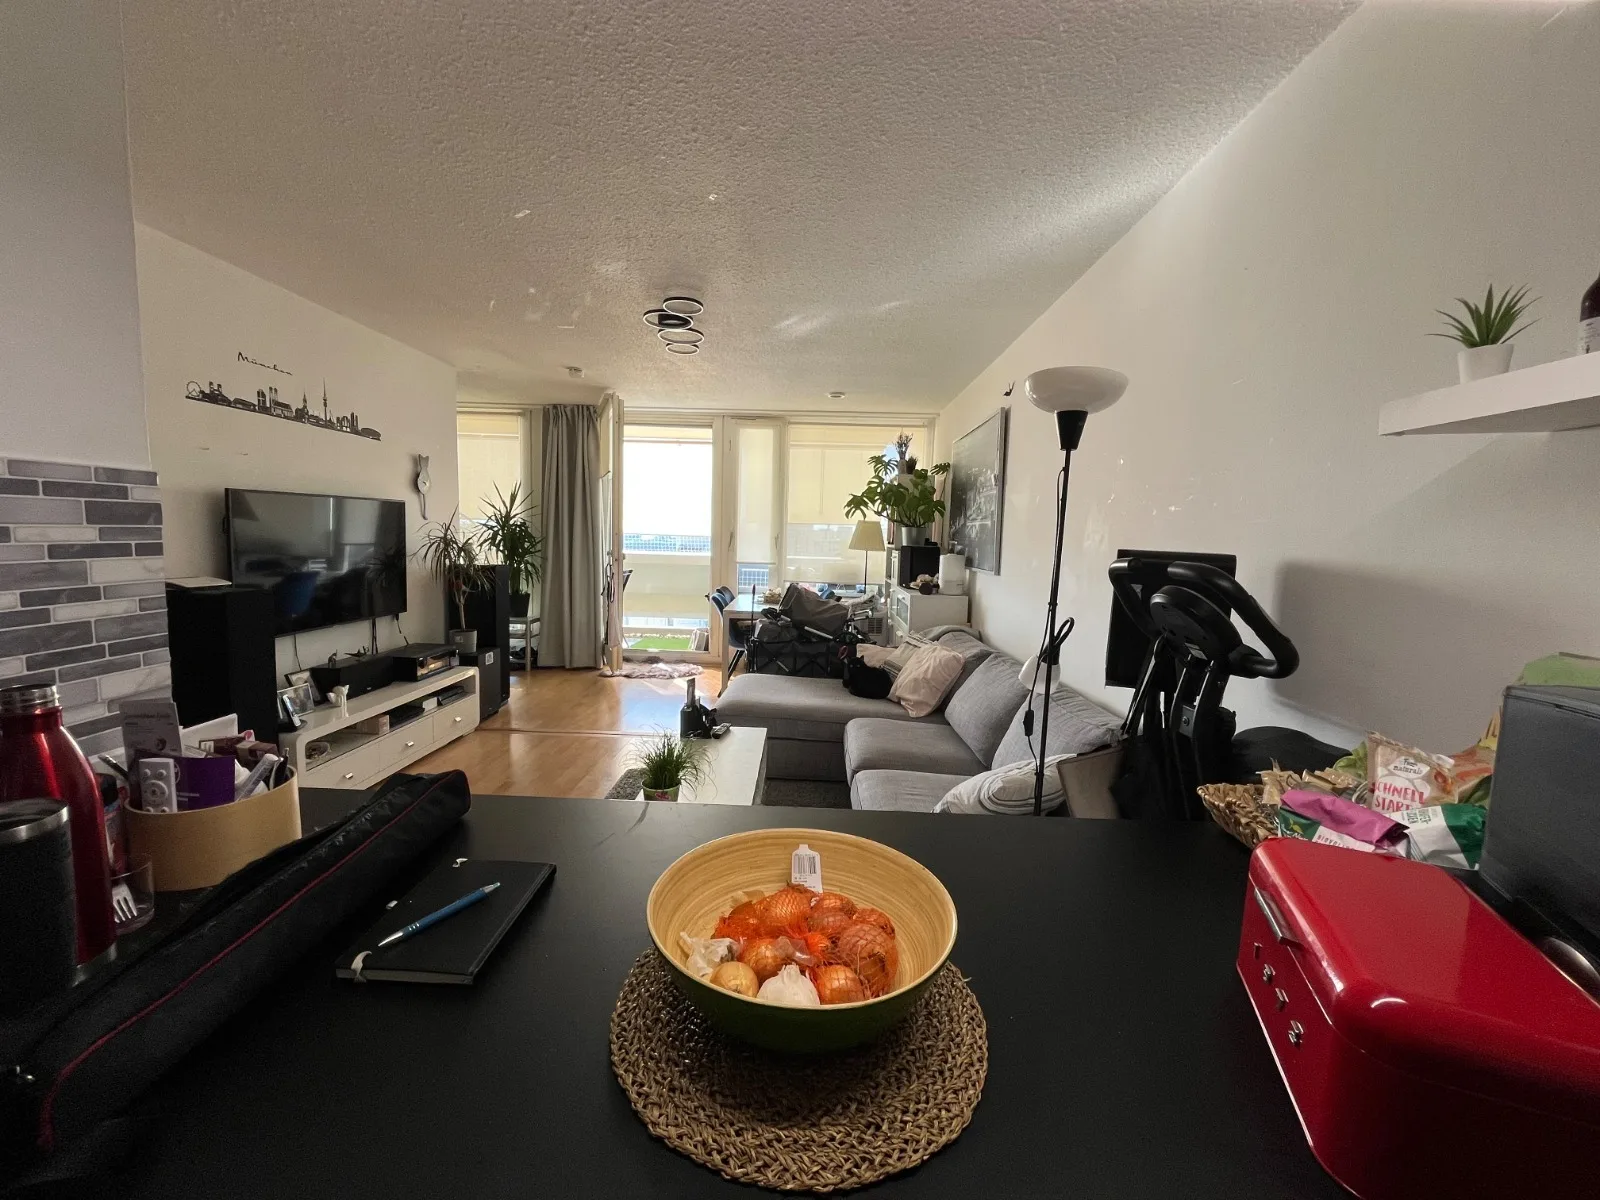
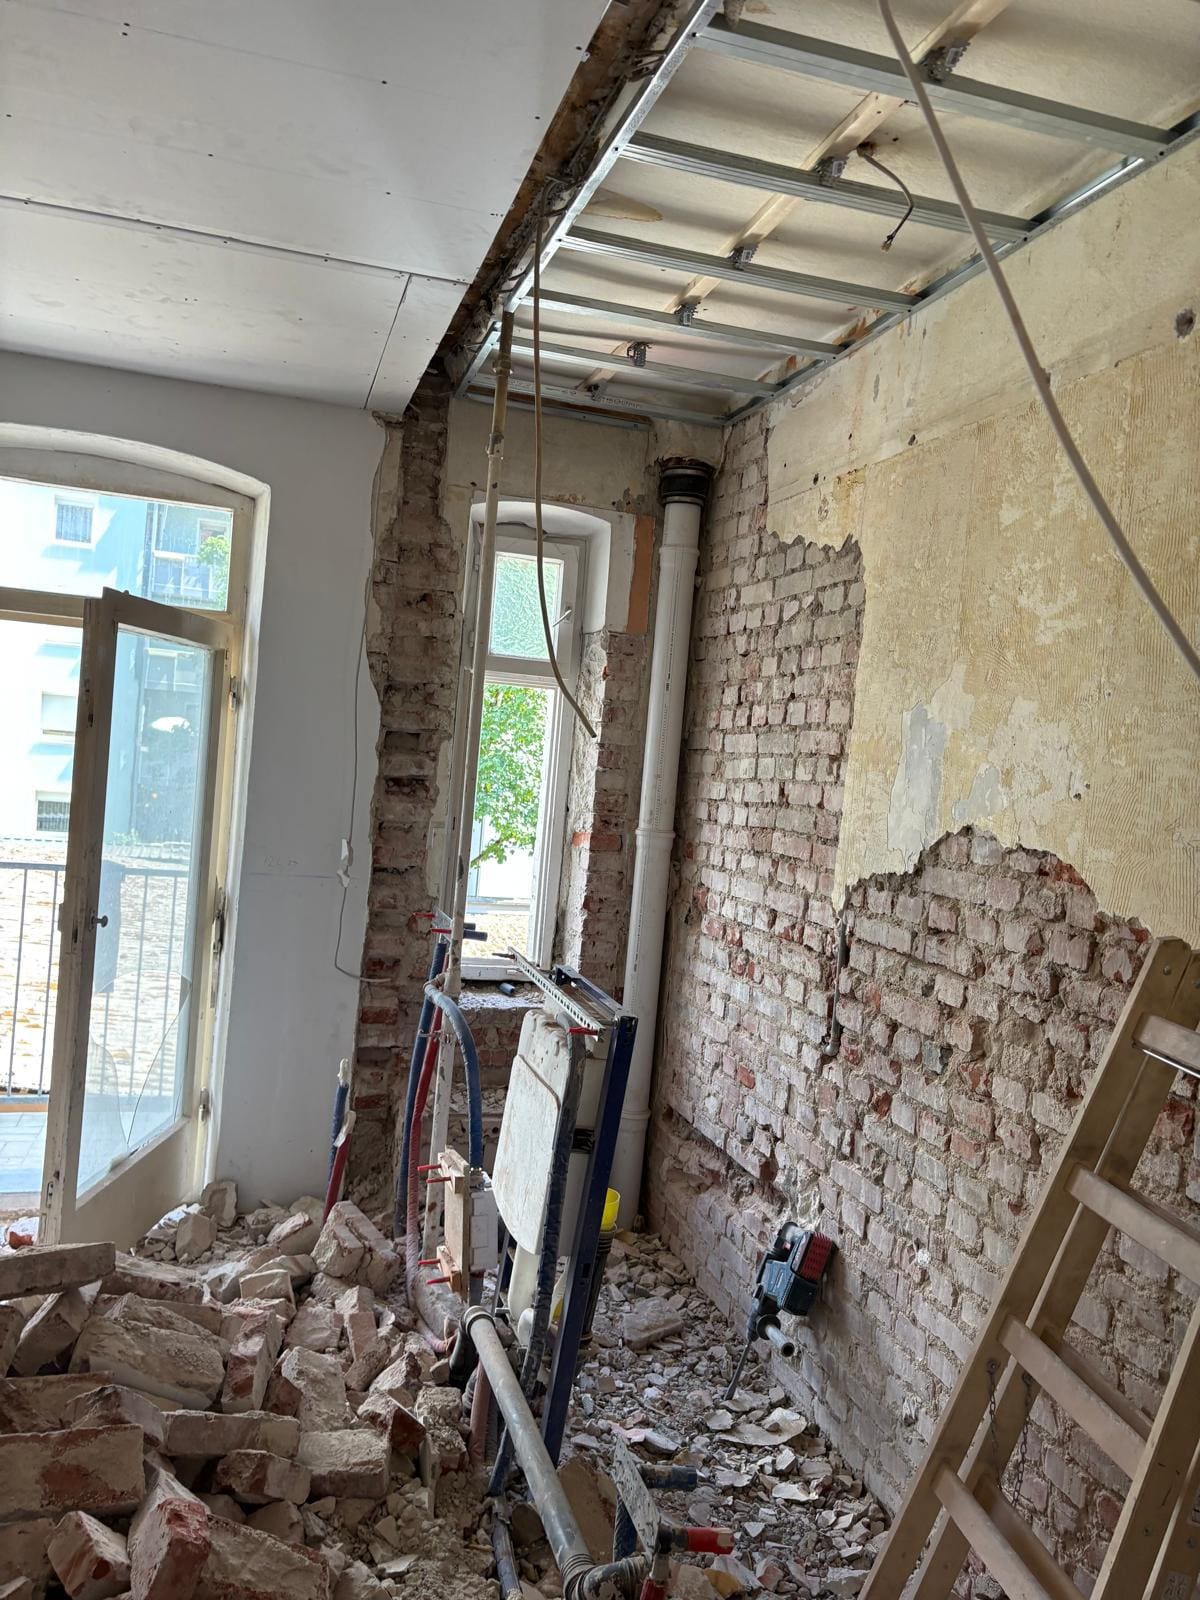
Before
d090c96a-5acb-43e9-9151-17c200f34e49
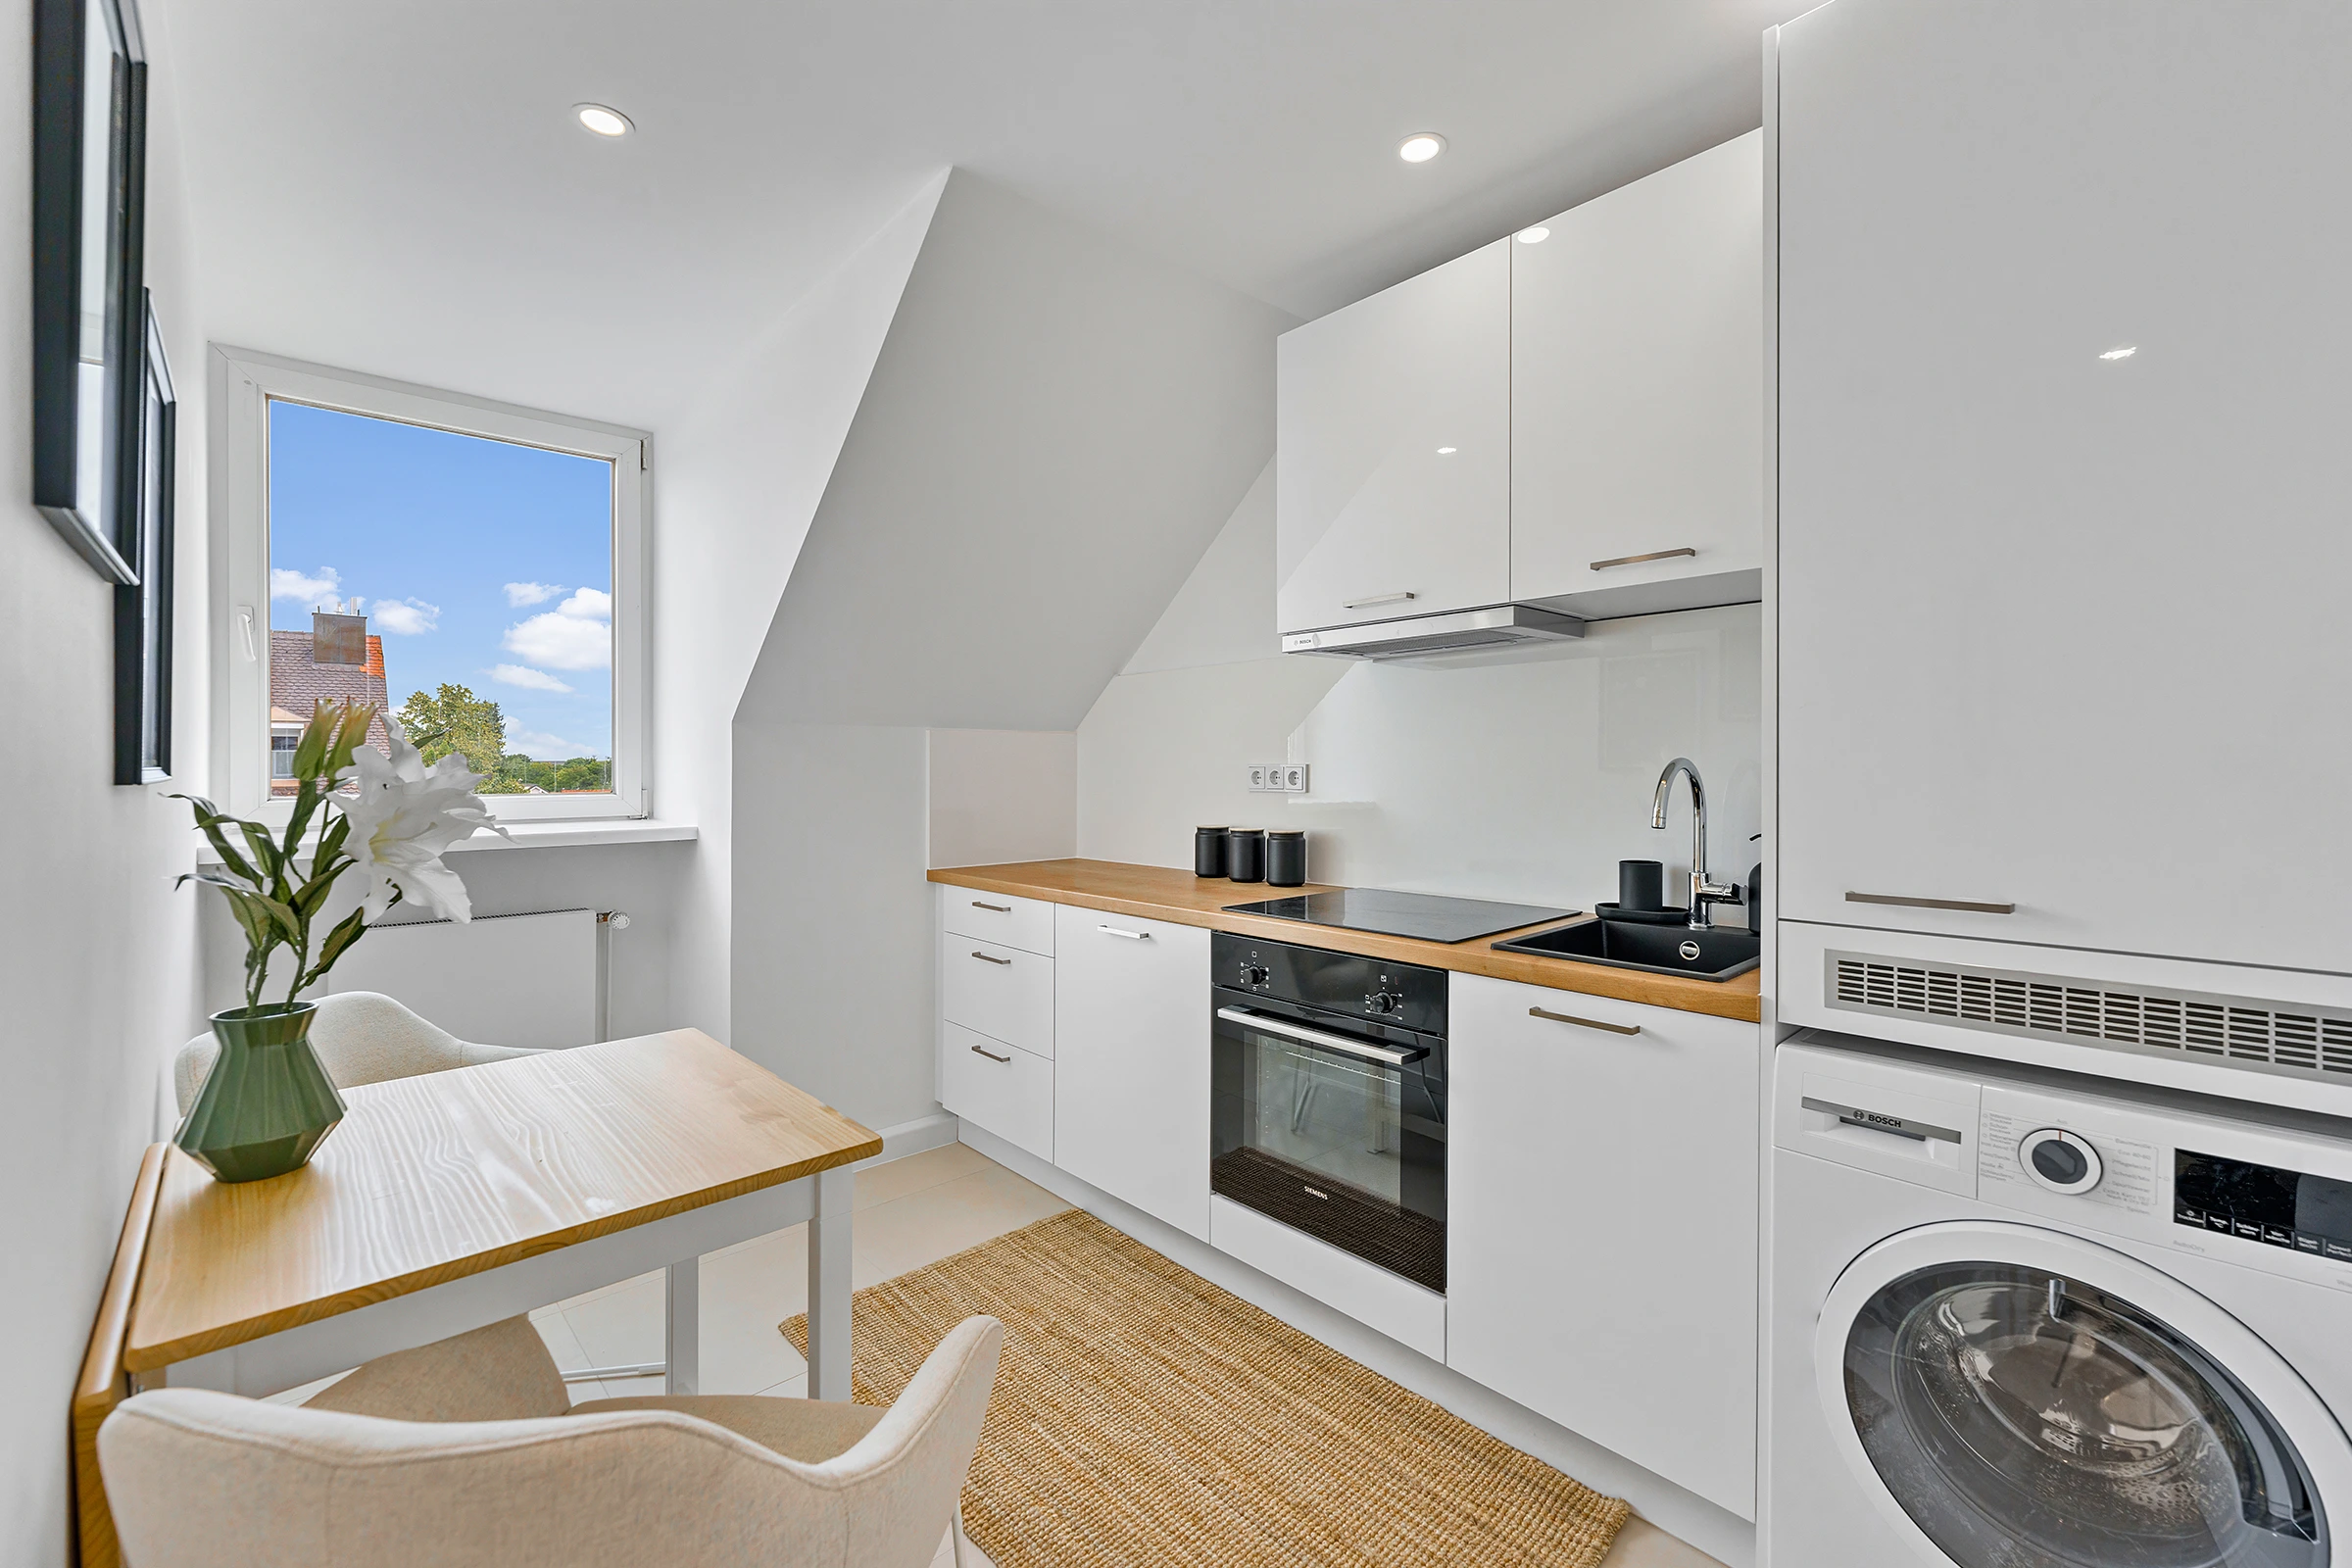
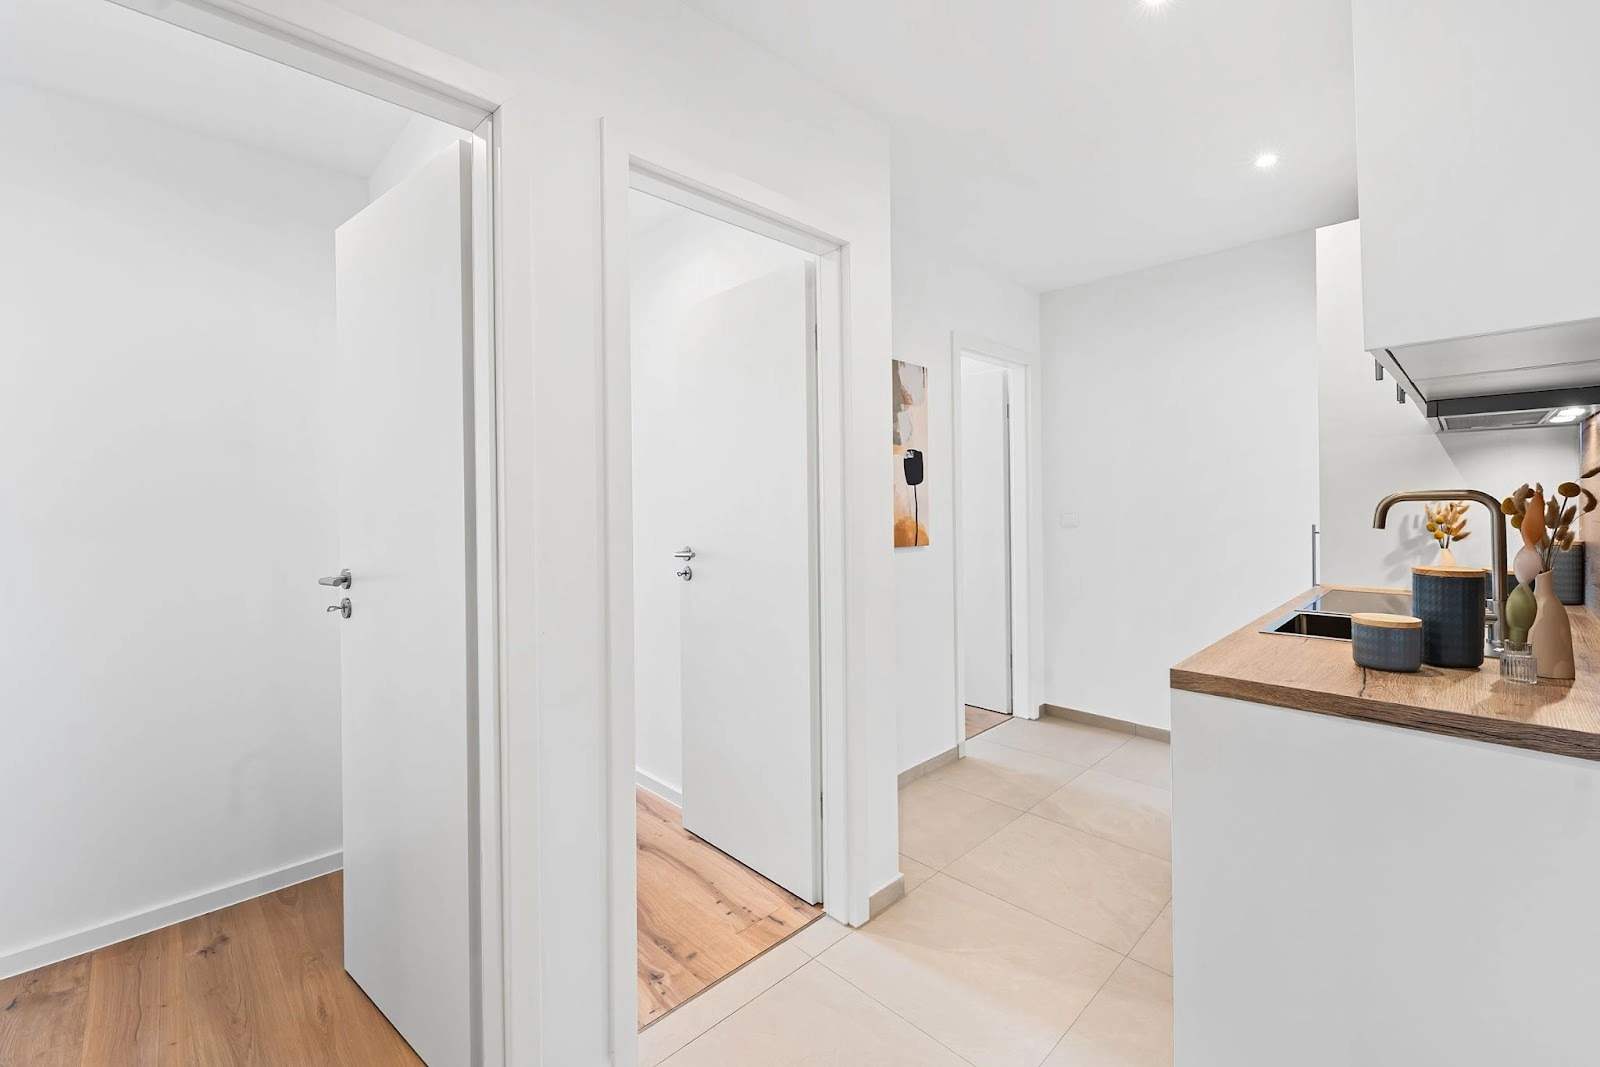
After
Kitchen
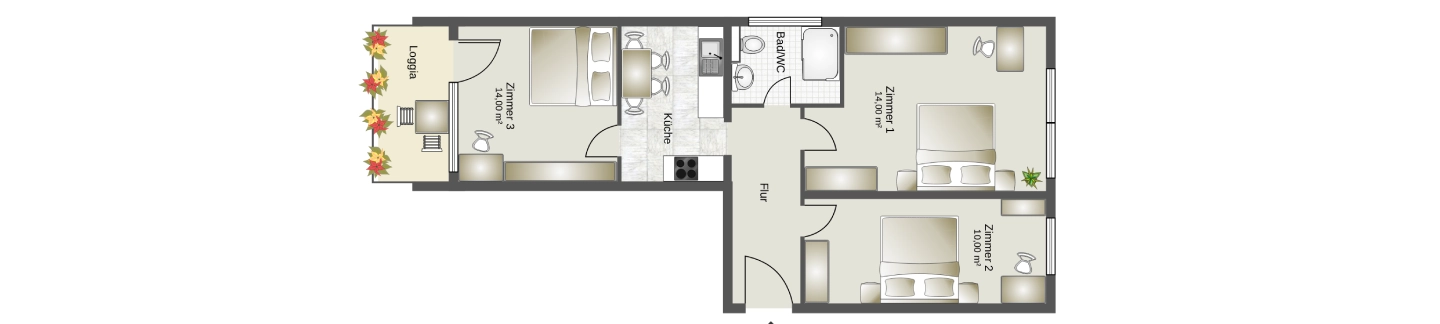
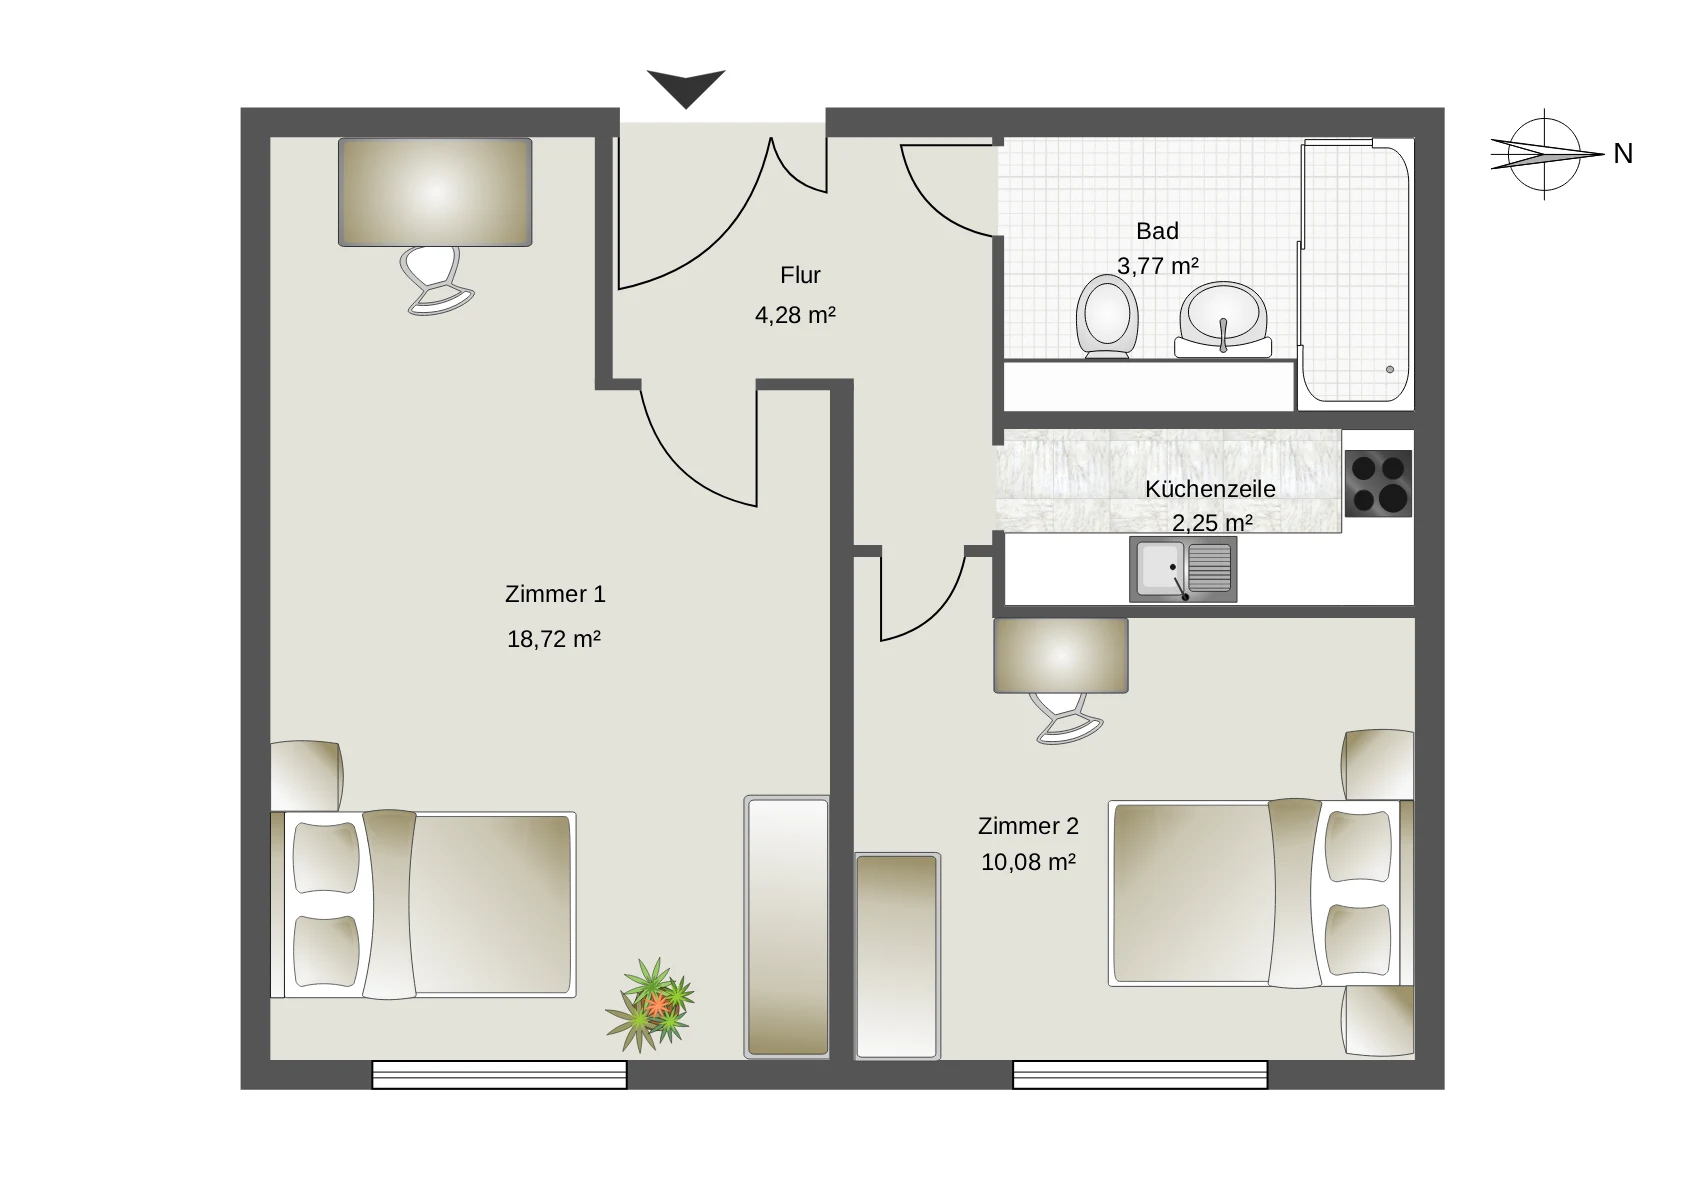
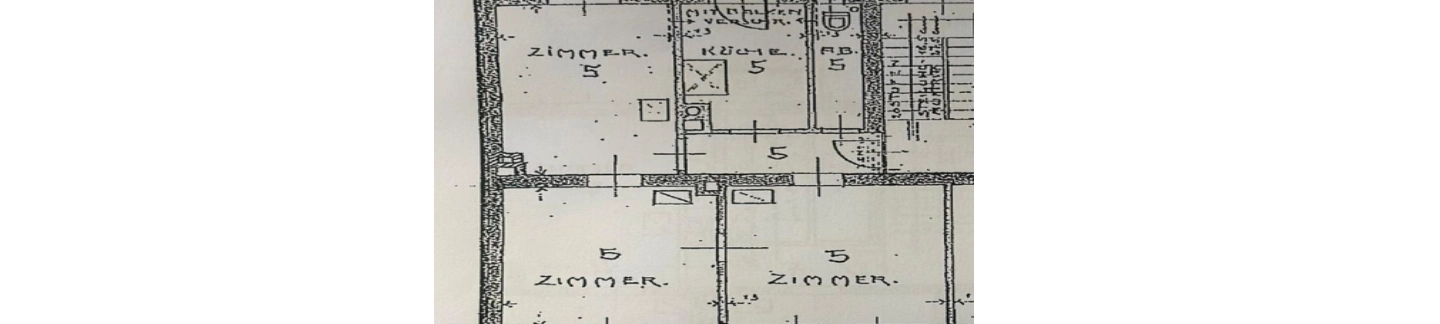
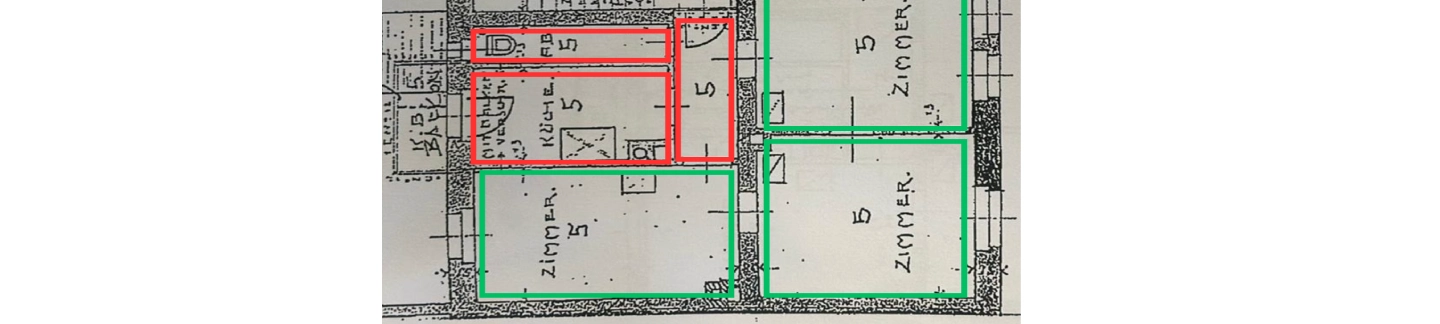
3% Yield
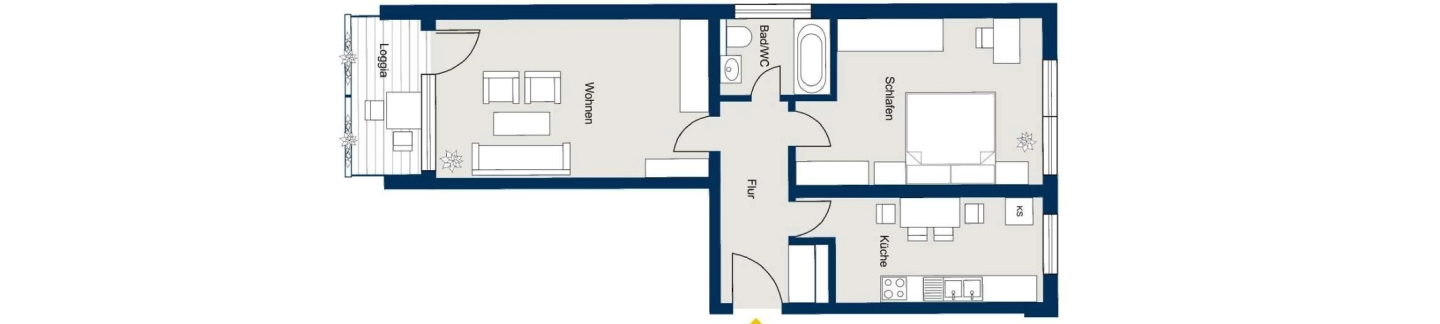
Appenzeller-layout-before-hor
5.2% Yield
appenzellerstr-layout-after
location mark Helene-Mayer-Ring, Munich
watermark
Before
Helene-Mayer-Ring(before)
After
Helene-Mayer-Ring(after)
2,7% Yield
pre-original2
5,4% Yield
Helene-Mayer-Ring-Layoutafterpng2
location mark Gertrud-Bäumer-Straße, Munich
watermark
Before
Gertrud-Bäumer-Straße(before)
After
Gertrud-Bäumer-Straße(after)
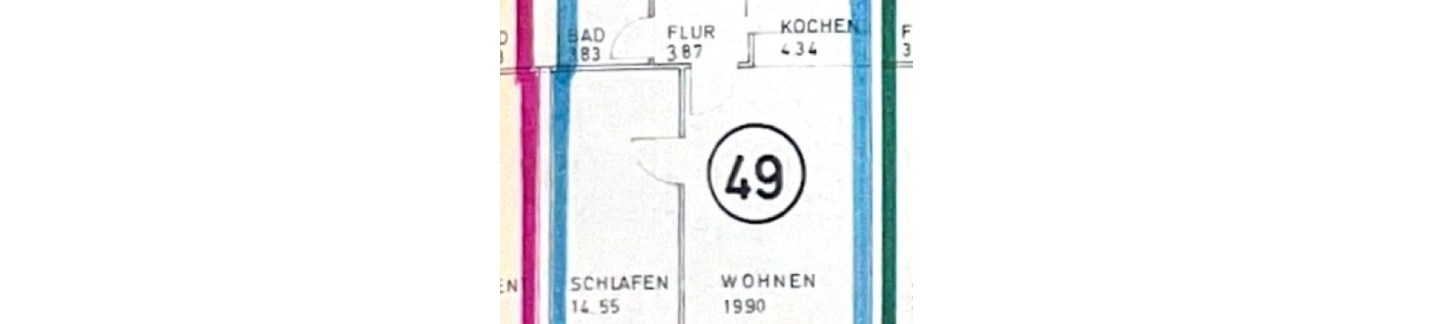
3,0% Yield
Layout (pre)
5,1% Yield
Layout (post)
location mark Gabelsbergerstraße, Nürnberg
watermark
Before
WhatsApp Image 2026-01-08 at 13.08.14 (1) (2)
8,3% Depreciation
After
Gabelsbergerstraße-after-img
2,2% Yield
Gabelsbergerstraße-layout-before
4,9% Yield
Gabelsbergerstraße-layout-after
location mark Wehneltsteig, Berlin
watermark
Before
Screenshot
7% Depreciation
After
Wehneltsteig-after-img
3,2% Yield
Wehneltsteig-layout-before
6,5% Yield
Verlin-layout-after-img (1) (2)

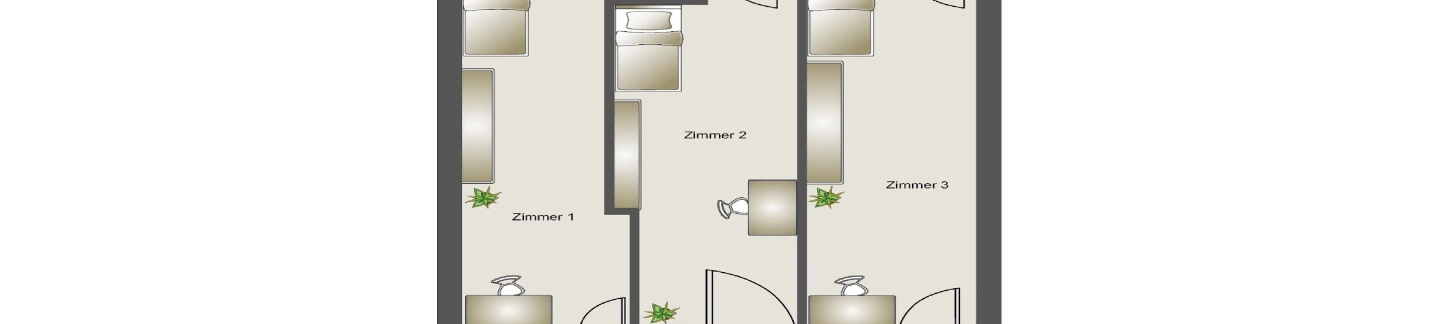
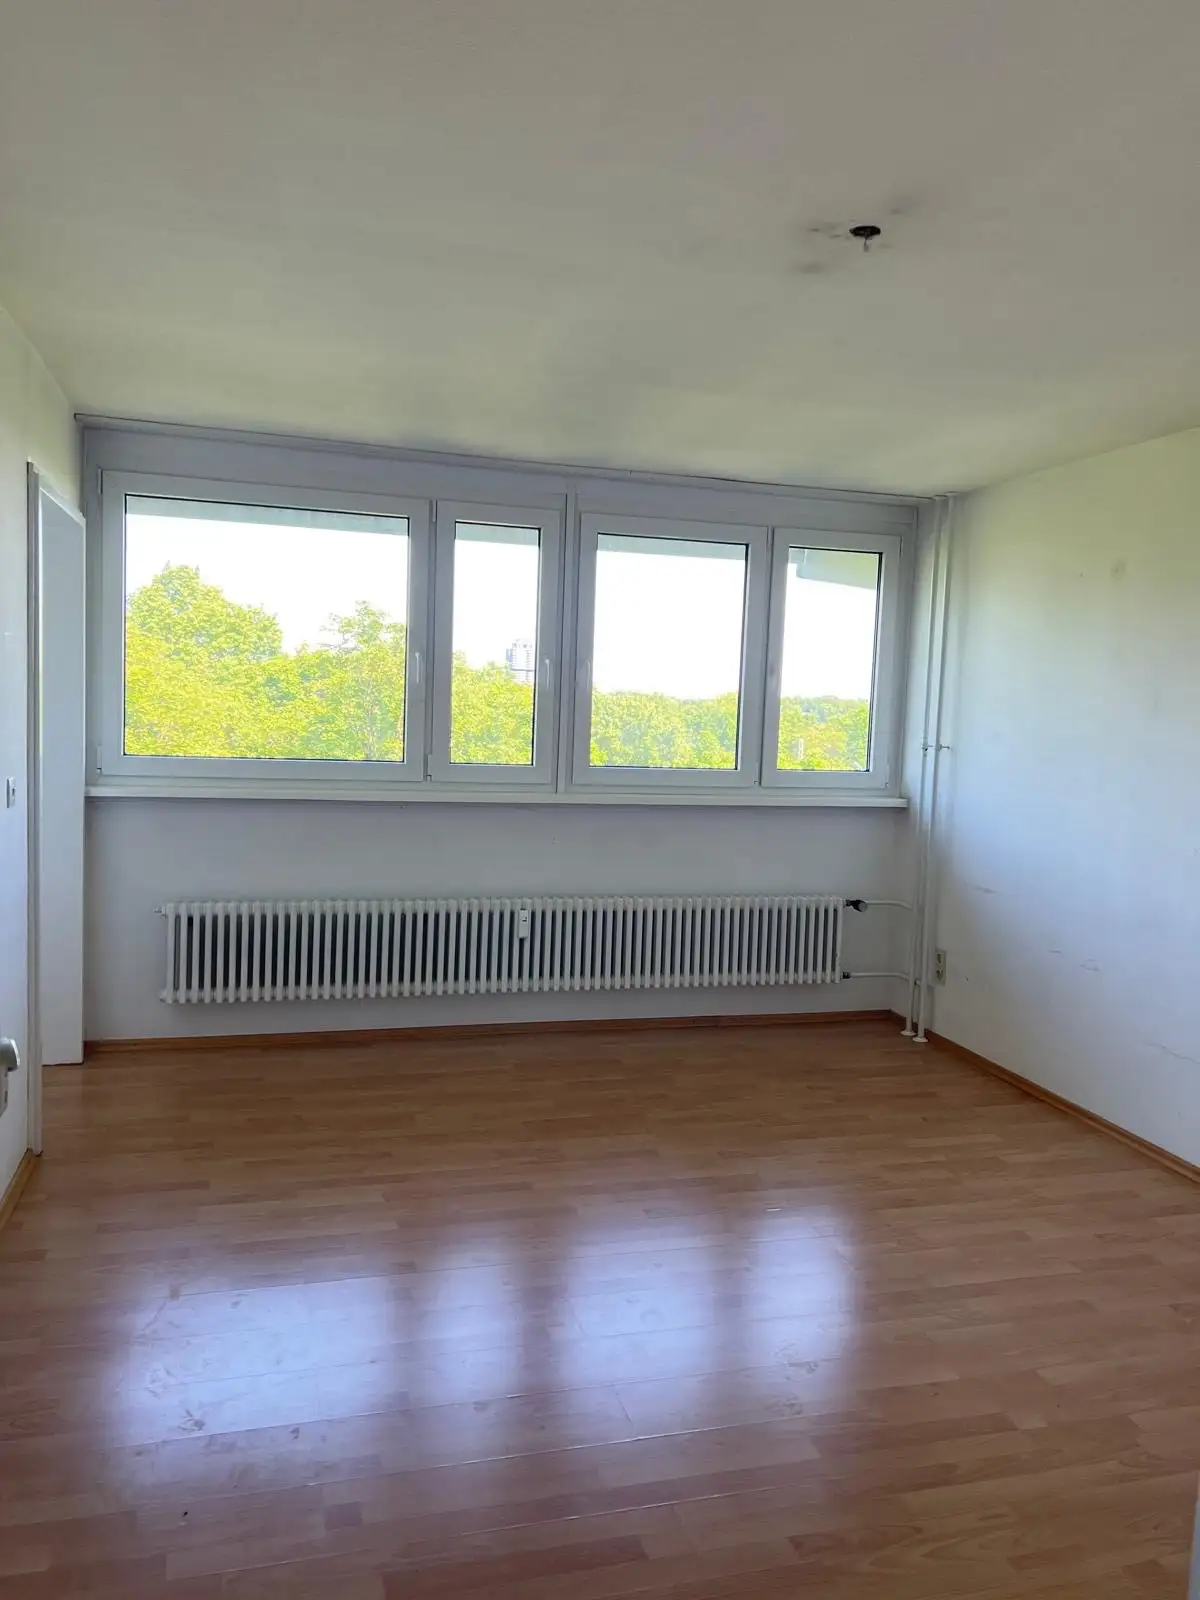
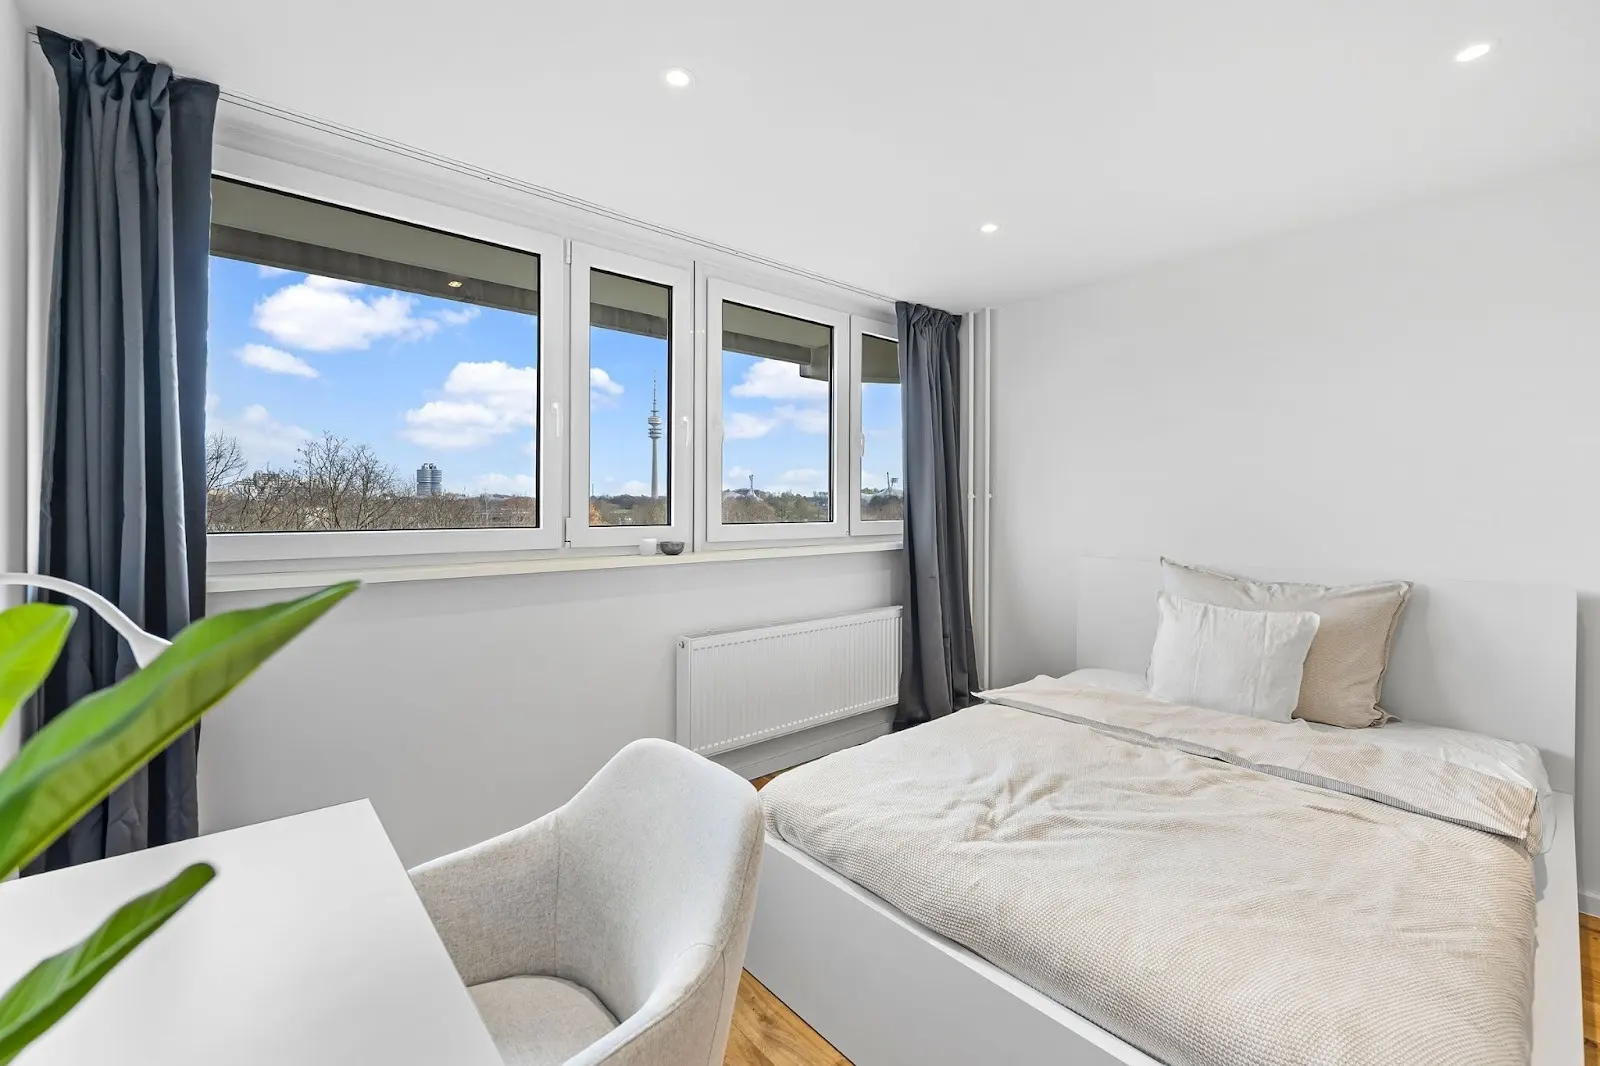
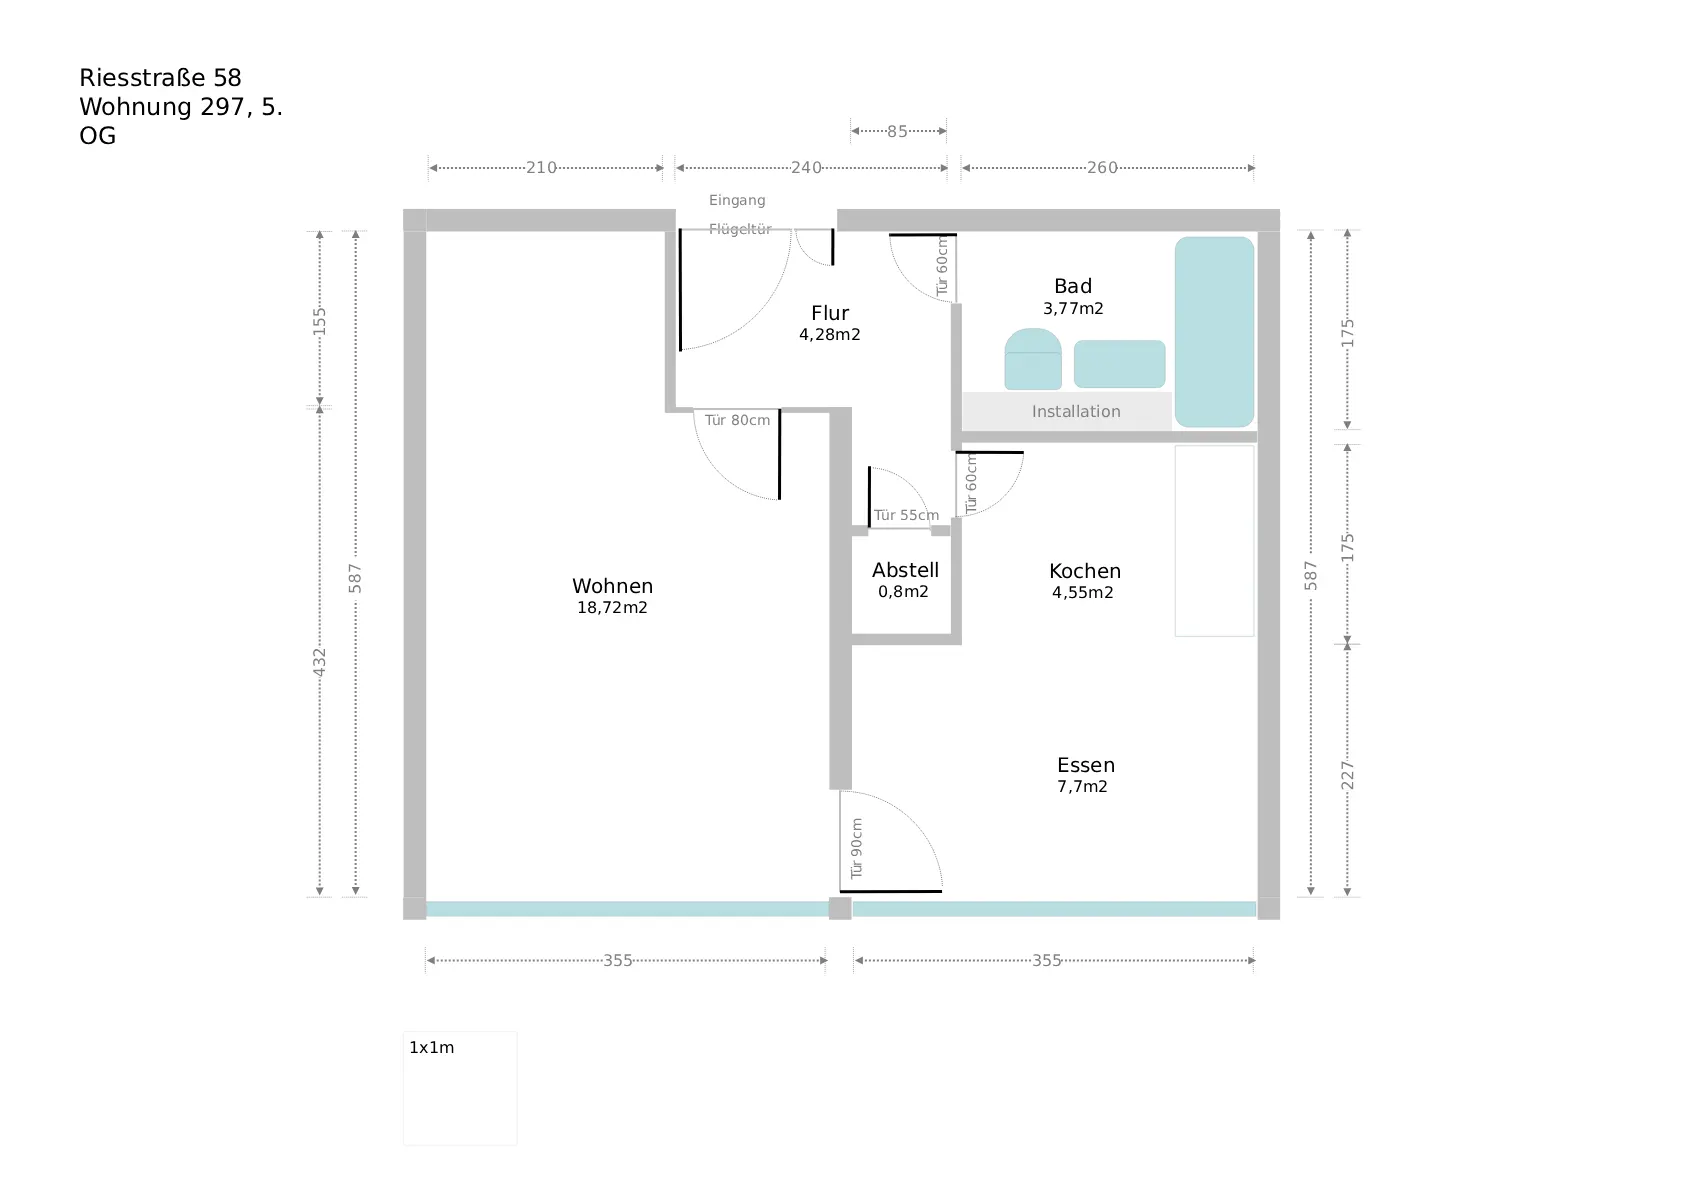
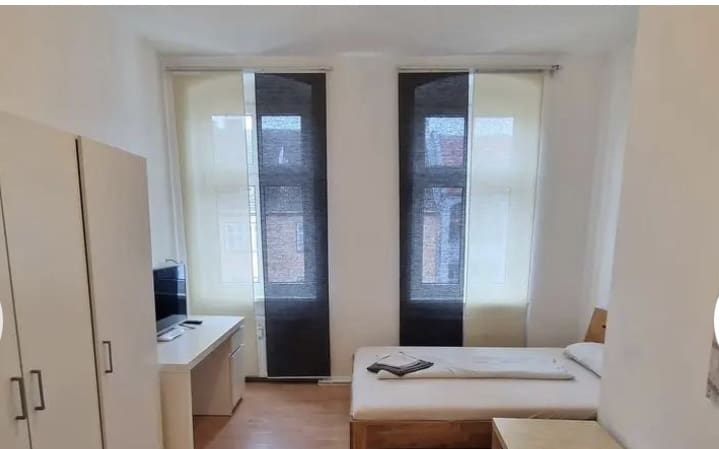
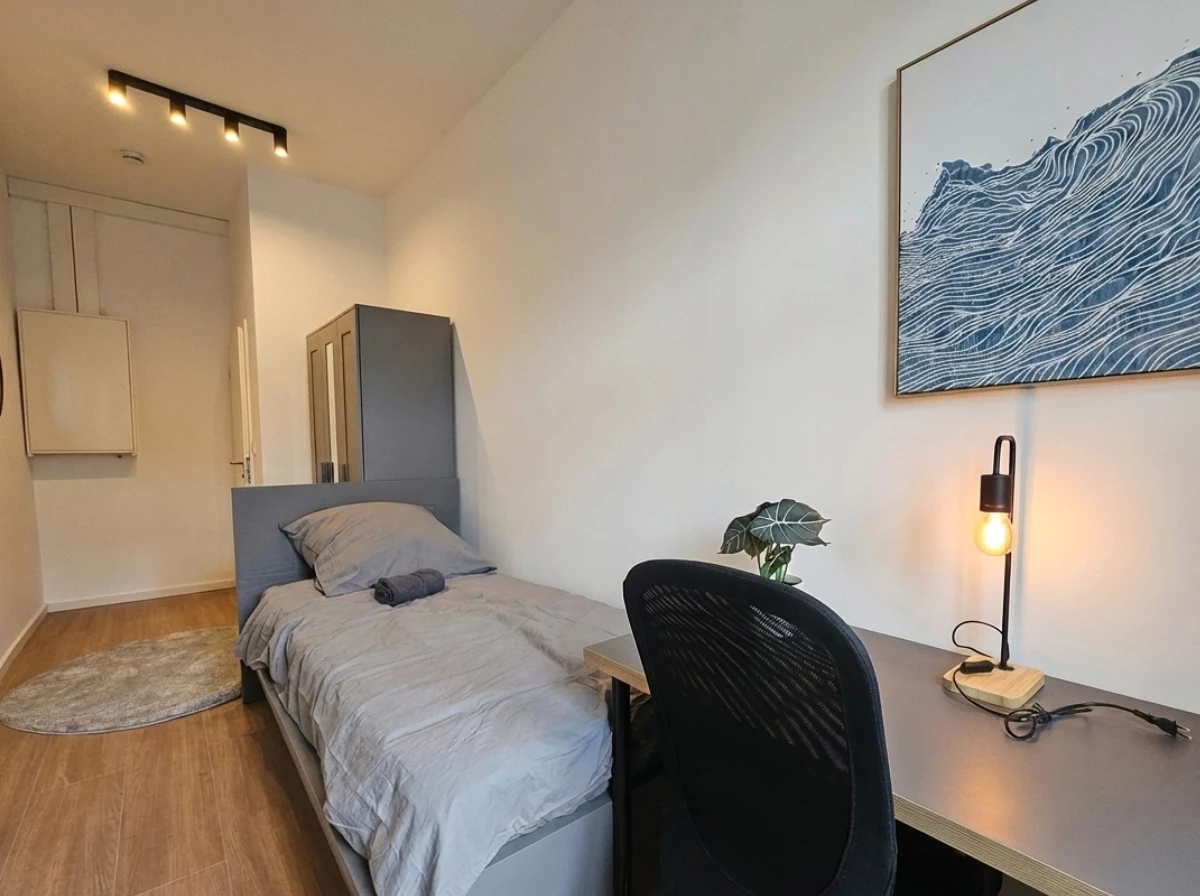
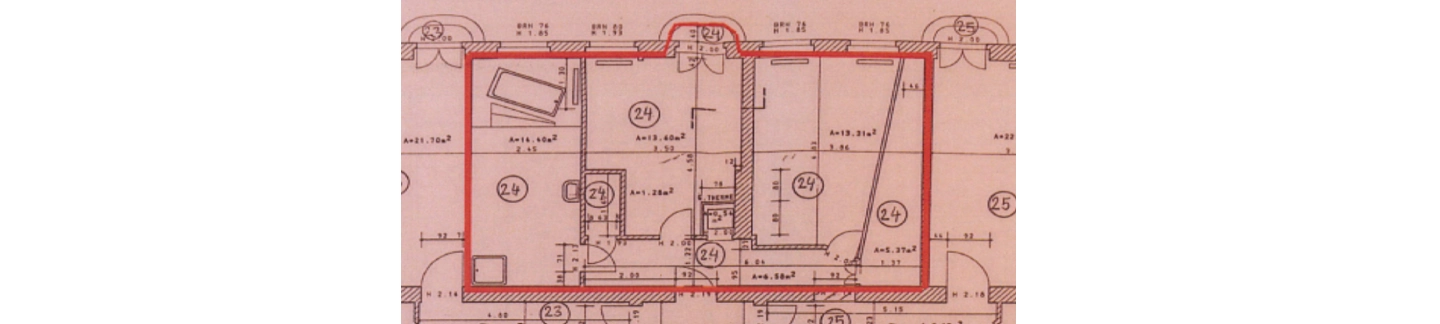
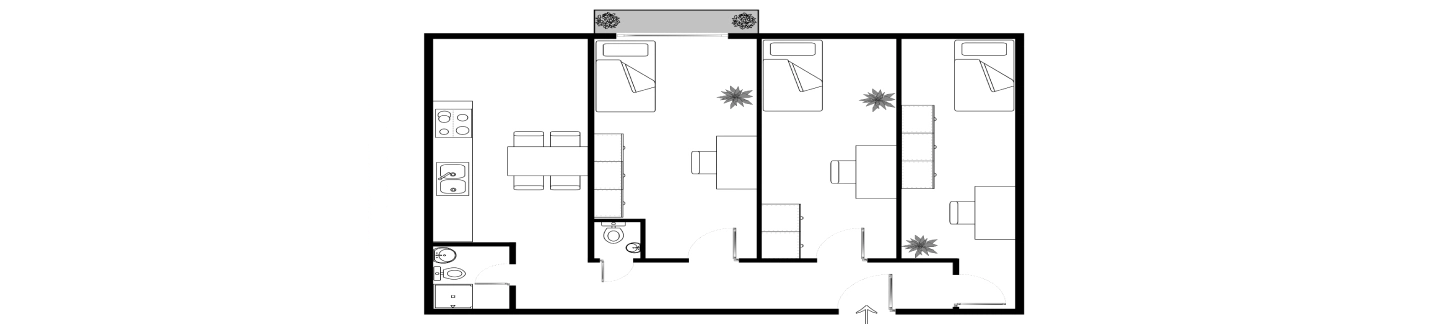
These are individual properties after repositioning, not market averages. The yield marked “after” is what that specific unit produced once it was let on new terms, which is why it sits above the city figure. City-wide gross yields run lower: across the 25 German cities we track they range from 2.6 to 4.9 percent, with Munich at 3.2 and Berlin at 4.1. Those figures, and the source behind each one, are in our city reports. The tax figures shown here depend on the building, the purchase structure and your personal situation. They are not a forecast for any other property.
background image

WHY INVEST IN GERMAN REAL ESTATE

Germany’s real estate investment market offers strong long-term potential driven by a housing shortage of over 800,000 homes. Rising immigration and limited new construction continue to increase rental demand across major cities. For investors and expats, property investment in Germany provides stable rental yields, capital appreciation and long-term financial security in one of Europe’s strongest economies.

wc-icon1

Tax-efficient wealth accumulation

Germany’s tax framework provides highly attractive advantages for real estate investors, particularly for high-income expatriates.

Read More Plus
model points
house model
wc-icon2

Strategic capital leverage through german banking

Germany’s financing environment offers investors the ability to control high-value assets with exceptionally low entry capital.

Read More Plus
model points

Our Offerings

LDP Group provides a seamless, end-to-end real estate investment service for expats in Germany. From identifying high-potential investment properties to securing optimal mortgage financing in Germany, we manage every step of the property investment process, including tenant placement, rental property management and coordination with trusted tax advisors. Beyond your first purchase, we develop a tailored long-term real estate portfolio strategy designed to grow your property value, generate stable rental income and maximize the tax benefits of real estate investment in Germany.

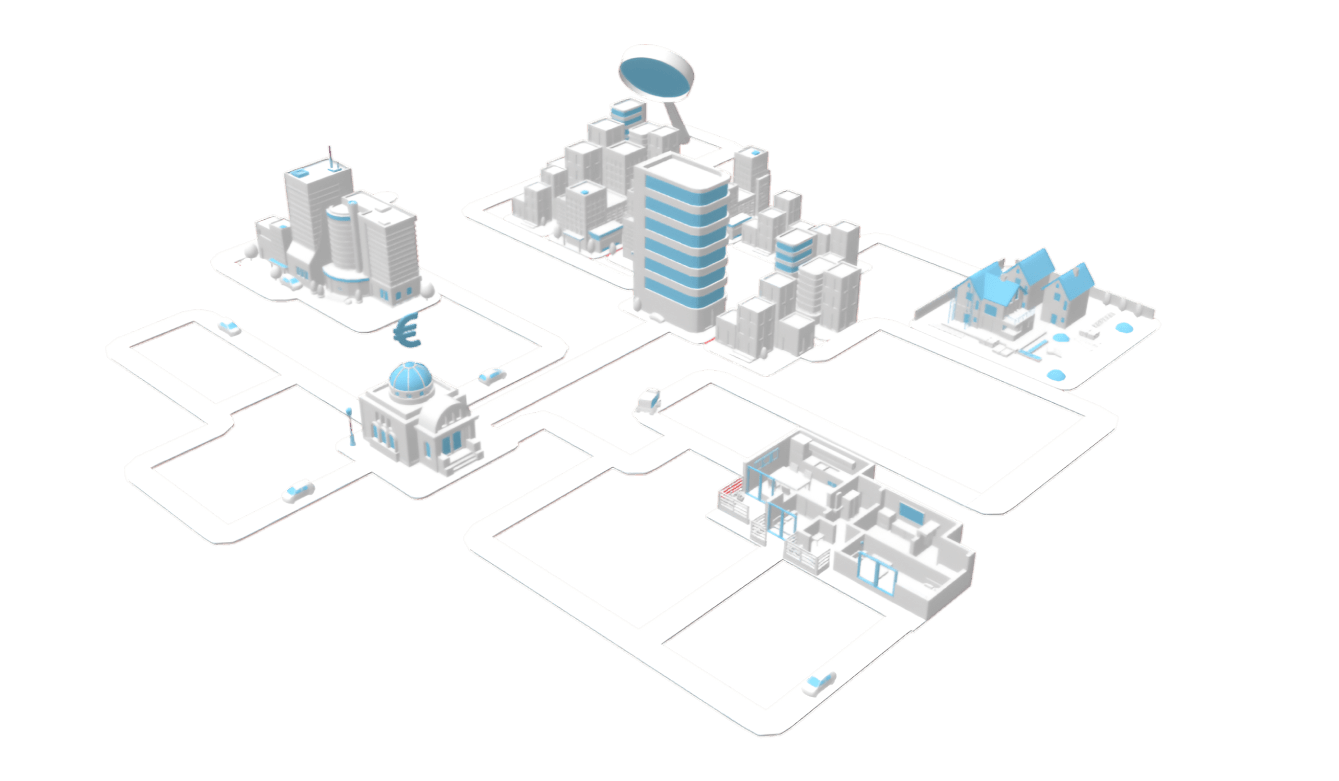
city model
Click the blinking Dots to view more

Tap a service to read what it includes.

What You Gain by Partnering with Us

Now is the perfect time to invest in properties that pay for themselves through secure rental income. Few opportunities rival the long-term wealth potential of real estate today. Thanks to our extensive network and diverse expertise, we identify the ideal properties with optimal financing tailored to your needs. Often, we provide our clients with not only new investment opportunities but also fresh perspectives that can transform their financial futures.

Image
01 01

We find your perfect property match

01 01

We find your perfect property match

  • Conducts in-depth market analysis to identify high-return investment opportunities.
  • Recommends properties tailored to your goals and budget.
  • Assists in choosing neighborhoods with strong rental demand and growth potential.
  • Evaluates property value, expected returns, and future appreciation prospects.
  • How we source and acquire property in nine German cities
prt1
02 02

We tailor cost-effective financing

02 02

We tailor cost-effective financing

  • Step-by-step assistance throughout the purchasing process, from property search to closing.
  • Negotiation support to secure the best price and favorable terms for your investment.
  • Coordination with legal professionals for due diligence, contract review, and documentation.
  • Guidance on financing options and assistance with mortgage applications if needed.
  • How we arrange mortgage financing for expats and EU residents
prt2
03 03

We guide you through all official procedures

03 03

We guide you through all official procedures

  • Strategic marketing cooperations with companies to attract qualified tenants quickly.
  • Professional photography and compelling property listings to showcase your rental units effectively.
  • Thorough tenant screening processes to ensure reliable and financially stable renters.
  • Lease preparation and negotiation to establish clear terms and protect your interests.
  • How we structure the purchase for tax, with Helm & Partner
expand-img
04 04

We take over renting & managing your properties

04 04

We take over renting & managing your properties

prt4
05 05

Long-term support & portfolio development

05 05

Long-term support & portfolio development

  • As your trusted partner, we remain by your side even after the purchase, assisting you in Building/expanding your real estate portfolio
prt5

Your JOURNEY As A Real Estate Investor

fullmap fullmap_mob
pointer3
Individual fitting
pointer2
Financing analysis
pointer1
Property selection
pointer5
Viewing
pointer4
Reservation
pointer6
Notary
pointer7
Acceptance of service
pointer8
Claim tax benefits

Frequently asked questions

LDPGroup operates on an internal commission structure, generating revenue by facilitating transactions between property owners, construction companies, and prospective buyers. This means that LDPGroup is compensated by the housing providers themselves, rather than charging an additional fee to the customer. Our business model is designed to provide a seamless and cost-effective home buying experience, with no hidden charges passed on to the end consumer. LDPGroup’s expertise and industry relationships allow us to connect qualified buyers with premier properties, while earning revenue through the standard provisions built into the developer’s sales process. This structure ensures transparency and aligns our incentives with delivering the best possible outcome for our clients. By working closely with housing providers, we’re able to leverage our market knowledge and negotiating power to secure favorable terms: benefits that are directly passed on to you, the homebuyer.

Co-living, called a Wohngemeinschaft or WG in Germany, means letting one existing apartment room by room to several tenants who each hold their own contract, instead of to a single household. The rooms are priced separately, so the flat as a whole earns more than one tenant would pay for it. In LDP's published client cases, anonymised and aggregated, a 3 to 5 room co-living conversion moved from an average cold rent of 1,201 euros a month before to 2,369 euros after, twice the starting rent, and from a gross yield of 2.8 percent at purchase to 5.4 percent after conversion. The cost side is real: more turnover, more management, and each room contract is a full tenancy under German law, including the rent cap in Berlin and Munich. That is why our own management company runs the rooms afterwards.

Co-living investment in Germany: yields, rules, process

We source in nine German cities: Berlin, Munich, Nuremberg, Erlangen, Fuerth, Duesseldorf, Cologne, Stuttgart and Karlsruhe. The focus is existing buildings, co-living conversions and full renovation projects, from a purchase price of 100,000 euros; we do not sell new builds. Rental management is available in every one of those cities, through our own company FairMieten in Berlin and Bremen and vetted partners elsewhere, for example Miethelden in Munich. Separately from what we sell, we publish verified market data for 25 German cities: price per square metre, average cold rent, gross rental yield and vacancy, with every figure carrying the source it came from, plus dedicated investor guides for Munich, Berlin and Nuremberg. So you can check a city against the numbers before you ever speak to us.

Investing in Munich property as an expat, with Berlin and Nuremberg guides alongside
Three mechanisms do the work, and all three apply to a property you let out, not to a home you live in yourself. Depreciation under § 7 EStG writes off the building, never the land: 3.0 percent a year for buildings completed from 2023, 2.0 percent for 1925 to 2022, 2.5 percent before 1925, plus a 5.0 percent declining-balance option under § 7 Abs. 5a EStG where construction started between 1 October 2023 and 30 September 2029. Deductions: mortgage interest, running costs and maintenance come off the rental income. The ten year rule: under § 23 EStG the gain on a private sale is free of tax once you have held the property for ten years. None of it is automatic. It depends on how the purchase is structured, and the depreciation rate depends on the build year of the specific building.

AfA depreciation explained

LDP Group partners with banks and mortgage providers in Germany to help our customers secure financing for property purchases in under 21 days, which is what makes an off-market deal workable at all, because those sellers do not wait. Our partners handle pre-approval, the comparison across lenders, refinancing and insurance, often through free consultation funded by lender commissions. What we put in front of you before any of that starts is the equity number, because it decides whether the purchase happens. If you live in Germany with German income, published requirements start at around 10 percent down plus the purchase costs. If you live abroad, our working figure is 40 to 50 percent of the price in equity, a 50 to 60 percent loan-to-value, with the purchase costs on top of that.

German mortgages, and how to get out of one

With LDP as your reliable partner, we offer high-yielding exclusive off-market properties in Germany’s most popular location for real estate investors: Munich. We are here to assist non-German speakers to invest successfully. Our experts guide you step by step on how to build a six-figure fortune with a modest monthly contribution. Sit back and let us assist you in achieving stress-free wealth generation. Over the last two years, we’ve amassed a real estate portfolio of over 8 figures, propelled by our distinctive strategy. What’s more, we continue to expand our portfolio with new properties each month. Hundreds of customers have already benefited from our system and are now successful landlords. And we firmly believe: you can achieve this too!

How we work

Yes, and there is no permit, no residency requirement and no citizenship test. German law places no restriction on foreign ownership of residential property, and the process is the same one a German buyer goes through: the contract has to be recorded by a notary under § 311b Abs. 1 BGB, and the transfer is only final once the land registry enters you as the owner. You do not have to be in the room for the notary appointment. Representation by power of attorney is routine, but the land registry will only act on one that satisfies § 29 GBO: the original document with a notarially certified signature, and an apostille if it was certified outside Germany.

Buying and financing without living in Germany

How long you will hold it decides this, more than which city you pick. Across the 25 cities we track, gross rental yields run from 2.6 percent in Hamburg to 4.9 percent in Wuppertal, a spread of about 2.3 percentage points. Against that, purchase costs of roughly 5.5 to 8.5 percent of the price are spent on day one and never come back. Spread over a five year hold, they cost 1.1 to 1.7 percentage points of yield every single year, which is more than the gap between the best and the worst city in the country. Hold for ten years and the same costs weigh half as much, and § 23 EStG makes the gain on a private sale free of tax. Short horizons are where German property goes wrong, far more often than bad cities.

Should you buy if you might leave in five years?

Where you live decides this, not which passport you hold. Banks assess whether your income is verifiable and durable and how much equity you bring; citizenship appears in none of the published criteria we found. If you live in Germany with German income, published requirements start at around 10 percent down plus the purchase costs. If you live abroad, the lender pool is smaller and the equity requirement jumps: our working figure from arranging this financing is 40 to 50 percent of the price in equity, which is a 50 to 60 percent loan-to-value. That is lender convention, not law, and no statute sets a ceiling. Rates on a ten year fixed ran 4.05 to 4.38 percent on 15 September 2026 depending on the loan-to-value band, and they move daily, so treat any rate you read anywhere, including here, as date-stamped rather than current.

What non-residents actually need

Budget roughly 5.5 to 8.5 percent of the purchase price on top of the price, depending on the federal state and on whether an agent is involved. Property transfer tax is the largest piece and is set per state and runs from 3.5 to 6.5 percent: 3.5 percent in Bavaria; 5.0 percent in Baden-Württemberg, Lower Saxony, Rhineland-Palatinate, Saxony-Anhalt and Thuringia; 5.5 percent in Bremen, Hamburg and Saxony; 6.0 percent in Berlin, Hesse and Mecklenburg-Vorpommern; 6.5 percent in Brandenburg, North Rhine-Westphalia, Saarland and Schleswig-Holstein. Notary and land registry add about 2 percent, are statutory under the GNotKG, and are therefore identical everywhere and not negotiable. Agent commission, where an agent is involved, costs the buyer 2.98 to 3.57 percent by state convention, capped at half the total commission on consumer purchases under §§ 656a to 656d BGB. The part people miss: a lender will normally not finance any of this. It comes out of your own money on top of the deposit.

Purchase cost calculator

Across the 25 German cities we track, gross rental yields run from 2.6 percent in Hamburg to 4.9 percent in Wuppertal, with a median of 4.0 percent. Munich sits at 3.2 and Berlin at 4.1, so the pattern is not simply big city against small one. Individual units can beat their city's average, particularly after a repositioning, which is why the cases further up this page sit higher. The city figure is the honest starting point. Those are gross figures: annual cold rent against purchase price, before any cost at all. Net yield is what you actually keep, and management, maintenance, the non-recoverable part of the service charges, vacancy and income tax take a real share of the gross out. Every one of the 25 figures on our site carries the source it was read from and the date it was read.
Rental yield calculator

An off-market property is one that is never publicly listed, so it does not show up on the portals or in a portal search. The upside is less competition, and sometimes a price that has not been bid up by a viewing queue. The part worth being straight about: no listing also means no comparison set, so you cannot benchmark the asking price the way you can against twenty similar flats on a portal. That makes two checks matter more than they otherwise would, an independent valuation and the price per square metre for that specific district rather than for the city as a whole. We publish the second one for every city we cover.

Which city, and should you buy at all?
No. Non-residents can own and let German property, and remote ownership is normal; this is how our EU-resident clients buy. Two consequences are worth knowing before you start. Financing gets harder: expect a smaller lender pool and 40 to 50 percent equity, rather than the roughly 10 percent a resident with German income may be offered, and we do not arrange financing for buyers living outside the EU. The rent is taxed in Germany from the first euro. Under § 49 EStG your rental income is German-source income, and § 50 Abs. 1 EStG has the effect that the basic allowance, 12,348 euro in 2026, is added back onto your taxable income instead of exempting the first slice of it. The notary appointment itself is handled by power of attorney, notarised abroad with an apostille or certified at a German consulate, so remote ownership does not mean flying in to sign.
Buying German property remotely: the power of attorney guide

No. What moves your terms is your employment contract and your residence status, not your passport, and citizenship appears in none of the published lender criteria we found. Where the permit does bite is equity: published requirements run from around 10 percent down for permanent residents and EU citizens to 20 or 30 percent for temporary permits. An EU Blue Card counts as a temporary permit, but it also shortens the road to permanent settlement, which is what moves you into the better band. Under § 18c Abs. 2 AufenthG that is 27 months with basic German and 21 months with sufficient German, so the language certificate is worth six months of materially better financing terms.

What lenders actually assess

As read on 15 September 2026, a ten year fixed ran 4.05 percent on best-case terms, 4.11 percent at 80 percent loan-to-value and 4.38 percent above 90 percent. Shorter and longer fixes bracket that: 4.04 percent over five years, 4.24 percent over fifteen. Which band you land in depends on how much you borrow against the value, so the equity question sets your rate as much as the market does. Ten-year rates have moved above the 4% mark: the best available ten-year rate stands at 4.05% effective as of 14.09.2026, average loan-to-value bands at 4.0% to 4.4%. Dr. Klein reports a new high for the year on 08.09.2026 and attributes it to rising Bund yields driven by the Middle East conflict, higher inflation expectations and growing public debt. Its expert panel expects a sideways move with fluctuations in the coming weeks and a slight upward bias in the medium term, with a corridor of 3.3% to 3.9% for the best ten-year rate still the view for the second half of 2026. The ECB raised its key rates on 10.09.2026 as priced in. The Interhyp panel is split: half expect further increases over the next one to two months, half a sideways move, and for year-end the panel divides evenly between rising, stable and falling rates. Interhyp's CEO expects the level to stay above 4% for now. Rates move daily. We re-read this table every second Tuesday, and the date above is the day it was read, not today.

Full rate table by fixed period

German real estate is taxed in Germany whatever passport anyone holds and wherever anyone lives. If neither the deceased nor the heir was resident in Germany, § 2 Abs. 1 Nr. 3 ErbStG applies limited liability: only German-situs assets are taxed, and German real property is on that list under § 121 BewG. The catch is the allowance. § 16 Abs. 1 ErbStG gives a spouse 500,000 euro, a child 400,000 and a grandchild 200,000, but § 16 Abs. 2 cuts that pro rata under limited liability, in the ratio of the German assets to everything inherited from the same person over ten years. A child inheriting 300,000 euro of German property out of a 500,000 euro estate keeps three fifths of the 400,000, so 240,000 euro. This is decided by how the ownership is structured before the event, not after it.

Erbschaftsteuer explained

Buying wins on a long horizon and loses on a short one, and the crossover comes later in Germany than in most countries, because the entry costs are high and the rent side is well protected. Purchase costs of roughly 5.5 to 8.5 percent are spent the day you sign and never come back, which over a five year hold is 1.1 to 1.7 percentage points a year before anything else happens. On the other side, § 556d BGB caps a new letting in a designated tight market at 10 percent above the local reference rent, and § 558 Abs. 3 BGB caps increases inside a running tenancy at 20 percent over three years, 15 percent in tight markets. If you are reasonably sure of seven to ten years, buying usually wins. Under five, renting usually does.

Rent versus buy calculator

No. Germany has no golden visa and no residence permit granted for buying property. The residence categories in the Aufenthaltsgesetz turn on employment, self-employment, family reunification or study, and not one of them has a property test or an investment threshold. Owning a flat can support an application as evidence of stable circumstances, but it never creates a right of residence by itself. If anyone offers you German residency through a property purchase, that is not something German law provides. Naturalisation is a separate track again: since the reform in force from June 2024 the standard route is five years of lawful residence with B1 German and a civics test.

The EU Blue Card route

Not to buy. You meet it when you borrow. Arriving in Germany you have no Schufa file at all: foreign credit history does not transfer, and an empty file is not a bad score, it is an absence of data. Since March 2026 the score is a single figure from 100 to 999. Lenders weigh it alongside your income, your contract type and your equity, and equity is the lever that compensates for a thin file. That is also part of why buyers living abroad, who often have no German file whatsoever, meet a 40 to 50 percent equity requirement rather than a flat refusal.

Financing without a German record

Start with one existing flat, let long term, financed by a German bank and managed by someone on the ground. If you live in Germany you can usually finance up to 80 percent of the purchase price; purchase costs of roughly 5.5 to 8.5 percent depending on the state (transfer tax plus about 2 percent notary and land registry) always come from equity. The tax structure, depreciation on the building share, the land and building split and the treatment of renovation costs, is decided before the notary date, not at the first tax return. Our entry point is a purchase price of 100,000 euros, which is the property price, not the cash you need. The guide below walks through eligibility, cash needed, city choice, property type, the tax levers and who can help at each step.

How to start investing in German property as an expat, step by step

Self-manage if you live near the flat, read German, have one long-term tenant and the time for the annual operating cost statement (due within twelve months under § 556 Abs. 3 BGB), the deposit rules of § 551 BGB and the occasional repair. Hire a manager once you live abroad, own several units or let room by room, because then the work scales with the number of tenants, not with the square metres. German managers usually charge a percentage of the cold rent plus a placement fee; LDP's model is a flat fee from 30 euros per tenant per month with no percentage of rent and no placement fee, and third-party repairs billed at cost after your approval. The comparison page sets out the tasks, the legal deadlines and both fee models with a worked example.

Self-managing vs professional rental management in Germany

A mortgage broker arranges the loan and is paid by the bank; it does not find, price or manage the property. A turnkey seller sells properties from its own stock, often new builds, with financing and management arranged around the sale. A financial adviser offers property as one product next to insurance and pensions. LDP is a full-service investment firm: we source an existing building on the open market, run the purchase calculation, which both founders review, coordinate financing through the broker FM Zinswerk with no fee to you, decide the tax structure with the tax firm Helm & Partner before the notary date, and set up management before the first tenant. We do not sell new builds, do not finance buyers outside the EU and do not give tax advice ourselves. The comparison page lists ten providers by type, quoting only what their own websites say.

Expat property investment services in Germany compared